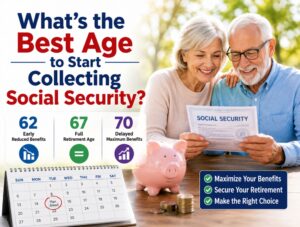
What’s the Best Age to Start Collecting Social Security?. When planning for retirement, one of the most important financial decisions Americans face is determining the best age to start collecting Social Security. While many people assume there is a single “perfect” age, the reality is far more complex. Your ideal claiming age depends on your health, financial needs, work plans, family history, life expectancy, marital status, taxes, and long-term retirement goals.
For millions of retirees, Social Security retirement benefits serve as the foundation of retirement income. Choosing to claim benefits too early may provide immediate financial relief but can permanently reduce monthly payments. Waiting longer often results in significantly larger monthly benefits, yet it requires delaying income during the early years of retirement.
As life expectancy continues to increase and retirement becomes more expensive, understanding how Social Security works has never been more important. Rising healthcare costs, inflation, housing expenses, and long-term care needs mean every retirement dollar matters. A thoughtful claiming strategy can potentially add tens of thousands or even hundreds of thousands of dollars over a lifetime.
Whether you’re approaching age 62, nearing your Full Retirement Age (FRA), or considering delaying benefits until age 70, making an informed decision can greatly improve your financial security.
This comprehensive guide explains everything you need to know, including:
- How Social Security retirement benefits are calculated
- Pros and cons of claiming at every age
- Factors that influence the best claiming strategy
- Common mistakes retirees make
- How married couples should coordinate benefits
- Tax implications
- Health considerations
- Financial planning tips for a secure retirement
Let’s begin by understanding the basics.
Understanding How Social Security Retirement Benefits Work
Before deciding when to claim benefits, it’s essential to understand how the Social Security system calculates your monthly payment.
Social Security retirement benefits are based primarily on:
- Your lifetime earnings
- Number of years worked
- Payroll taxes paid into the system
- Your claiming age
Your earnings history determines your Primary Insurance Amount (PIA), which represents the benefit you receive at your Full Retirement Age.
Your claiming age then adjusts that amount either upward or downward.
Generally speaking:
- Claiming before Full Retirement Age permanently reduces benefits.
- Claiming after Full Retirement Age increases benefits through delayed retirement credits.
- Waiting until age 70 provides the highest monthly benefit available.
Because these adjustments are permanent, your claiming decision affects every monthly payment for the rest of your life.
What Is the Earliest Age You Can Collect Social Security?
Most Americans become eligible to claim retirement benefits at age 62.
Although this is the earliest possible age, it also comes with the largest permanent reduction in benefits.
For example:
Suppose your Full Retirement Age benefit would be:
- $2,000 per month
Claiming at age 62 could reduce that amount to roughly:
- $1,400–$1,500 per month
That reduction continues for life.
Many retirees underestimate how much smaller their checks will be when claiming early.
While receiving benefits sooner sounds attractive, lower monthly payments may create financial challenges later in retirement, especially if you live into your 80s or 90s.
What Is Full Retirement Age?
Your Full Retirement Age (FRA) depends on your birth year.
For most people retiring today, FRA falls between:
- Age 66
- Age 67
At Full Retirement Age:
- You receive 100% of your earned benefit.
- There are no permanent reductions.
- Earnings limits disappear if you continue working.
- Benefit calculations reach their standard amount.
Many financial planners consider FRA an important milestone because it represents the point where benefits are neither reduced nor increased.
What Happens If You Wait Until Age 70?
One of the biggest advantages of delaying benefits is receiving delayed retirement credits.
Every year you delay after Full Retirement Age increases your monthly benefit by approximately 8% until age 70.
This increase is guaranteed by Social Security.
For example:
Benefit at Full Retirement Age:
- $2,000/month
At age 70:
- Approximately $2,480/month
That difference continues for the remainder of your life.
Over 20 or 30 years of retirement, the cumulative increase can become substantial.
Comparing Benefits by Claiming Age
Here’s a simplified illustration.
| Claiming Age | Approximate Monthly Benefit |
|---|---|
| 62 | 70–75% of FRA benefit |
| 63 | Slightly higher |
| 64 | Higher |
| 65 | Around 85–90% |
| Full Retirement Age | 100% |
| 68 | About 108% |
| 69 | About 116% |
| 70 | About 124% |
While exact percentages vary depending on birth year, the overall pattern remains consistent.
Earlier claiming equals lower monthly income.
Later claiming equals larger monthly income.
Why Many Americans Claim at Age 62
Despite reduced benefits, many retirees still choose age 62.
There are several reasons.
Immediate Income Needs
Some people simply cannot continue working.
Health issues, layoffs, caregiving responsibilities, or physically demanding jobs may force retirement earlier than planned.
For these individuals, early Social Security provides an important income source.
Job Loss Before Retirement
Workers in their early 60s sometimes struggle to find new employment after losing a long-term job.
Rather than exhausting savings, they begin collecting Social Security.
Health Concerns
Individuals facing chronic illness or shorter life expectancy often decide that receiving benefits sooner makes more financial sense.
If someone does not expect to live well beyond average life expectancy, delaying may not maximize lifetime benefits.
Family Circumstances
Some retirees need immediate cash flow to:
- Help adult children
- Care for aging spouses
- Cover medical expenses
- Pay off debt
Although claiming early reduces future income, immediate financial needs often outweigh long-term optimization.
Advantages of Claiming Social Security Early
There are situations where claiming at age 62 is appropriate.
You Receive Benefits Longer
Starting early means collecting payments for more years.
Although each check is smaller, the total amount received over a shorter lifespan may be comparable.
Financial Flexibility
Early benefits can reduce pressure on retirement savings.
Instead of withdrawing heavily from investment accounts during market downturns, retirees may use Social Security to supplement income.
Reduced Stress
Many retirees appreciate having guaranteed monthly income sooner rather than later.
Knowing that money arrives every month provides psychological comfort.
Helpful During Economic Uncertainty
Periods of recession, inflation, or market volatility can increase the appeal of stable monthly government benefits.
Disadvantages of Claiming Early
While early claiming has benefits, there are significant drawbacks.
Permanently Reduced Monthly Income
The reduction never disappears.
Every future benefit check remains smaller.
This affects:
- Retirement income
- Survivor benefits
- Inflation-adjusted increases
Lower Survivor Benefits
If one spouse dies, the surviving spouse may receive the deceased spouse’s benefit.
Higher lifetime benefits often translate into larger survivor benefits.
Waiting can therefore protect a surviving spouse financially.
Less Protection Against Inflation
Because annual cost-of-living adjustments are based on your existing benefit amount, larger starting benefits usually produce larger future increases.
Greater Risk of Outliving Savings
People are living longer.
Many retirees now spend:
- 25 years
- 30 years
- even 35 years
in retirement.
Higher monthly benefits can help prevent financial hardship later in life.
Why Waiting Until Age 70 Can Be a Smart Decision
Although delaying benefits requires patience, it offers several compelling advantages.
Larger Guaranteed Income
Unlike investment returns, delayed retirement credits are guaranteed by Social Security.
Higher monthly income continues for life.
Increased Financial Security
Long retirement periods expose retirees to numerous financial risks:
- Inflation
- Market downturns
- Medical expenses
- Long-term care costs
Larger Social Security payments help offset these risks.
Better Longevity Protection
No one knows exactly how long they will live.
If you reach age 90 or beyond, waiting until age 70 often produces substantially greater lifetime income.
Stronger Survivor Protection
For married couples, delaying the higher earner’s benefit can significantly improve survivor income.
This becomes particularly valuable for widowed spouses later in retirement.
Factors That Should Influence Your Decision
Choosing the best claiming age requires evaluating several personal factors.
Your Health
Ask yourself:
- Do chronic illnesses affect your life expectancy?
- Does your family typically live into their 90s?
- Are you physically healthy?
Individuals expecting longer lives often benefit from delaying benefits.
Your Employment Plans
Will you continue working?
If yes, delaying benefits may increase future income while avoiding earnings limitations before Full Retirement Age.
Your Retirement Savings
Those with substantial retirement assets have greater flexibility.
They may delay Social Security while withdrawing modestly from savings.
Those with limited savings may need benefits earlier.
Your Lifestyle Goals
Some retirees prioritize:
- Travel
- Hobbies
- Family experiences
- Volunteer work
Others prioritize maximizing income later in life.
There is no universal answer.
Your retirement lifestyle matters.
Inflation Expectations
Although Social Security includes annual cost-of-living adjustments, larger starting benefits provide stronger protection against rising expenses over time.
Healthcare, housing, and caregiving costs frequently rise faster than general inflation, making higher monthly benefits especially valuable for older retirees.
Taxes
Many retirees forget that Social Security benefits may be taxable depending on overall retirement income.
Your claiming strategy should be coordinated with:
- Retirement account withdrawals
- Pension income
- Investment income
- Required Minimum Distributions (RMDs)
Proper planning may reduce lifetime taxes while maximizing retirement income.
Common Misconceptions About Social Security
Many myths surround Social Security, leading retirees to make costly decisions.
Myth 1: Everyone Should Claim at Age 62
There is no one-size-fits-all strategy. While age 62 works well for some, delaying benefits may significantly increase lifetime income for others.
Myth 2: Waiting Is Always Better
Not necessarily. Individuals with serious health conditions or shorter life expectancies may receive greater lifetime value by claiming earlier.
Myth 3: Social Security Alone Is Enough
For most retirees, Social Security replaces only a portion of pre-retirement income. Additional savings, pensions, investments, or part-time work are often needed to maintain financial stability.
Myth 4: Benefits Never Change
Although your claiming age determines your base benefit, annual Cost-of-Living Adjustments (COLAs) can increase payments over time to help offset inflation.
Choosing the Best Age Based on Your Personal Situation
There is no universal answer to the question of when to begin collecting Social Security. Every retirement journey is different, and the right decision depends on your financial resources, health, family responsibilities, employment plans, and long term goals. Understanding how these factors work together can help you make a confident decision that supports both your current lifestyle and your future financial security.
If You Need Income Right Away
Many people retire earlier than they originally expected. Health concerns, unexpected job loss, family caregiving responsibilities, or physically demanding work may make it difficult to continue working into their late sixties.
If you have limited retirement savings and need a dependable source of monthly income, claiming Social Security at age 62 may be the most practical choice. Although your monthly benefit will be permanently reduced, receiving income sooner may help you cover essential living expenses without accumulating debt or exhausting your savings.
For retirees in this situation, financial stability today is often more important than maximizing future monthly payments.
If You Have Strong Retirement Savings
Retirees who have built substantial retirement savings usually have greater flexibility when deciding when to claim Social Security benefits.
If your retirement income includes savings from a 401(k), IRA, pension, investment accounts, or rental properties, you may be able to delay claiming Social Security until age 70. Waiting allows your monthly benefit to continue increasing each year after your Full Retirement Age, resulting in significantly higher lifetime income.
This strategy can provide several important advantages. You receive a larger guaranteed monthly benefit, stronger protection against inflation, greater financial security later in retirement, and increased survivor benefits for your spouse if applicable.
Many retirement professionals recommend using retirement savings during your early retirement years while allowing Social Security benefits to grow.
If Longevity Runs in Your Family
Family history is another important consideration.
If your parents, grandparents, or close relatives have generally lived into their late eighties or nineties, delaying Social Security may provide greater lifetime value. The longer you live, the more opportunities you have to benefit from higher monthly payments.
A larger guaranteed income can become especially valuable as healthcare expenses increase later in life. It can also reduce financial stress during retirement by providing dependable income regardless of market conditions.
If You Have Serious Health Concerns
While many people benefit from waiting, delaying benefits is not always the best strategy.
If you have a serious medical condition or expect a shorter than average life expectancy, collecting benefits earlier may allow you to enjoy your retirement income while you are still healthy enough to travel, spend time with family, and participate in activities you enjoy.
The goal of retirement planning is not simply to maximize dollars. It is to maximize your quality of life.
Social Security Strategies for Married Couples
Married couples have additional opportunities to optimize their Social Security benefits because each spouse’s decision can affect the other.
When deciding when to claim benefits, couples should consider their combined retirement income rather than focusing only on individual benefits.
Important factors include each spouse’s earnings history, age difference, current health, expected longevity, retirement savings, and future survivor benefits.
In many households, delaying the benefit of the higher earning spouse creates greater long term financial security. If one spouse passes away first, the surviving spouse may receive the larger benefit. Increasing that higher benefit can therefore provide valuable financial protection for the surviving partner.
Should Both Spouses Claim Benefits at the Same Time?
Not necessarily.
Many couples choose different claiming ages to balance immediate income with future financial security.
For example, one spouse may begin receiving benefits at age 62 while the higher earning spouse delays until age 70. This strategy provides current income while allowing one benefit to continue increasing each year.
Every family’s financial situation is unique, so coordinated retirement planning often produces better long term results than making independent decisions.
Social Security for Divorced Individuals
Many divorced retirees do not realize they may qualify for benefits based on a former spouse’s earnings record.
Eligibility depends on several factors, including the length of the marriage, your current marital status, your age, and the amount of benefits available.
Reviewing all available options before applying can help ensure that you receive the highest benefit you qualify for under Social Security rules.
Survivor Benefits for Widows and Widowers
The loss of a spouse is emotionally difficult, and it often creates financial uncertainty as well.
Social Security survivor benefits help provide continued financial support for eligible widows and widowers. Depending on your circumstances, you may qualify to receive benefits based on your late spouse’s work history.
This is one reason many financial advisors encourage the higher earning spouse to delay claiming benefits whenever possible. A larger retirement benefit today may become a larger survivor benefit for a surviving spouse in the future.
Working While Receiving Social Security
Many retirees choose to continue working after beginning Social Security benefits.
If you claim benefits before reaching your Full Retirement Age, your benefits may be temporarily reduced if your earnings exceed the annual limit established by Social Security. Once you reach your Full Retirement Age, these earnings limits no longer apply, and you may continue working without reducing your monthly benefit.
For many older adults, part time employment provides additional income while also supporting social interaction, mental stimulation, and a sense of purpose during retirement.
Understanding Taxes on Social Security Benefits
Some retirees are surprised to learn that Social Security benefits may be subject to federal income tax depending on their total retirement income.
Your taxable income may include retirement account withdrawals, pension payments, investment earnings, employment income, and rental income.
Carefully coordinating these income sources can reduce your overall tax burden throughout retirement. Many retirees benefit from discussing withdrawal strategies with a qualified financial or tax professional to create a tax efficient retirement income plan.
Inflation Can Significantly Affect Retirement
Inflation gradually reduces purchasing power over time.
Even relatively modest inflation can have a substantial impact during a retirement that lasts twenty five or thirty years.
Everyday expenses such as housing, groceries, healthcare, insurance, utilities, and transportation generally become more expensive as time passes.
Although Social Security provides annual Cost of Living Adjustments, retirees with larger starting benefits usually receive larger annual increases in dollar terms. This is another reason why delaying benefits can strengthen long term financial security.
Healthcare Costs Continue to Increase
Healthcare is one of the largest expenses many retirees face.
As people age, they often require more frequent medical appointments, prescription medications, dental care, vision care, hearing services, rehabilitation, and specialized treatments.
Planning for these costs is an important part of retirement preparation.
A higher monthly Social Security benefit can provide additional flexibility when paying for healthcare while reducing the need to withdraw large amounts from retirement savings during periods of unexpected medical expenses.
Many older adults also choose aging in place, remaining safely in their own homes while receiving the support they need to maintain independence and quality of life.
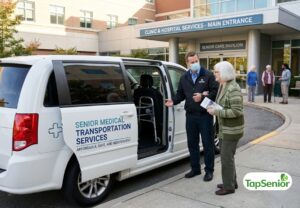
Reliable Transportation Supports Healthy Aging
Transportation is an essential part of maintaining independence throughout retirement.
Many older adults eventually decide to drive less frequently or stop driving altogether. Having dependable transportation allows seniors to continue attending medical appointments, grocery shopping, participating in community activities, visiting family members, and remaining socially connected.
Professional Senior Transportation Services provide safe and reliable transportation that helps older adults remain active while giving family caregivers greater peace of mind.
Access to dependable transportation also reduces missed medical appointments and encourages preventive healthcare, both of which contribute to healthier aging.
Retirement Is About More Than Financial Security
Although Social Security plays an important role in retirement planning, a fulfilling retirement includes much more than monthly income.
Successful retirees often focus on maintaining their physical health, strengthening relationships with family and friends, participating in volunteer opportunities, learning new skills, pursuing hobbies, and staying involved in their communities.
Financial stability provides freedom, but meaningful experiences create lasting happiness during retirement.
Common Social Security Mistakes to Avoid
Many retirees unintentionally reduce their lifetime retirement income by making avoidable mistakes.
One common mistake is claiming benefits immediately upon becoming eligible without first developing a comprehensive retirement plan.
Another mistake is failing to coordinate Social Security decisions with a spouse. Married couples often achieve better financial outcomes by planning together.
Some retirees underestimate how long they may live. With increasing life expectancy, retirement can easily last three decades or longer. Planning only for the early years of retirement may create financial challenges later in life.
Others overlook the long term effects of inflation. While annual increases help maintain purchasing power, beginning with a larger monthly benefit provides greater protection over time.
Finally, many people rely too heavily on Social Security alone. A diversified retirement income strategy that includes retirement savings, investments, pensions, and other assets can provide greater financial stability throughout retirement.
Frequently Asked Questions
Is age 62 always the wrong choice?
No. For individuals with immediate financial needs, limited retirement savings, or significant health concerns, claiming at age 62 may be the most practical decision.
Is waiting until age 70 always the best strategy?
Not necessarily. Waiting provides the highest monthly benefit, but your health, financial circumstances, and retirement goals should guide your decision.
Can I continue working after claiming Social Security?
Yes. Many retirees continue working. Before reaching Full Retirement Age, annual earnings limits may temporarily affect your benefits. After reaching Full Retirement Age, those limits no longer apply.
Do Social Security benefits continue increasing after age 70?
No. Delayed retirement credits stop accumulating at age 70, so there is generally no financial advantage to waiting longer.
Should I seek professional advice before claiming?
If your retirement situation involves multiple income sources, investments, pensions, or complex family circumstances, consulting a qualified financial advisor can help you make a well informed decision.
Building a Complete Retirement Plan
Choosing when to collect Social Security is only one piece of successful retirement planning.
A comprehensive retirement strategy should also address healthcare planning, emergency savings, monthly budgeting, housing decisions, long term care needs, insurance coverage, investment withdrawals, estate planning, and family financial goals.
Reviewing your retirement plan regularly allows you to adjust as your financial situation and personal priorities evolve over time.
Helping Aging Parents Make Smart Decisions
Adult children often play an important role in helping parents navigate retirement.
Families can support older loved ones by discussing retirement goals, organizing financial documents, reviewing available income sources, encouraging preventive healthcare, arranging dependable transportation, and exploring community resources that support healthy aging.
Open communication helps everyone make informed decisions while respecting the independence and personal preferences of older adults.
Final Thoughts
Determining the best age to start collecting Social Security is one of the most important financial decisions you will make during retirement.
There is no single age that works for everyone. Some retirees benefit from claiming early because they need immediate income or face health challenges. Others achieve greater long term financial security by waiting until Full Retirement Age or delaying benefits until age 70.
The best decision is one that aligns with your health, retirement savings, expected longevity, family responsibilities, and overall financial goals.
As you prepare for retirement, remember that Social Security is only one component of a successful retirement strategy. Combining thoughtful financial planning with healthy lifestyle choices, reliable Senior Transportation Services, strong family support, and community engagement can help you enjoy a retirement that is secure, active, and fulfilling.
By taking the time to understand your options and planning carefully, you can make informed decisions that provide confidence, independence, and peace of mind throughout your retirement years.
Bài viết liên quan: