Retirement Wealth Plan: How Senior Citizens Can Grow And Protect Their Money. Retirement is often described as the reward for decades of hard work. After years of building a career, raising a family, paying off debts, and saving diligently, many older adults look forward to enjoying a slower pace of life. However, retirement also introduces a new financial reality. Instead of earning a regular paycheck, retirees must rely on the wealth they have accumulated over the years. The biggest challenge is no longer simply making money it is making that money last.
Today’s retirees face a financial environment that is far different from what previous generations experienced. Rising healthcare costs, inflation, longer life expectancy, unpredictable financial markets, and changing tax rules all make retirement planning more complicated than ever before. A retirement that lasts 25 to 35 years is no longer unusual, meaning your savings may need to support you for decades.
This is why having a Retirement Wealth Plan has become one of the most important financial decisions any senior can make. Rather than reacting to market changes or making emotional investment decisions, retirees need a structured strategy that balances growth with protection.
Many people mistakenly believe retirement investing ends the moment they stop working. In reality, retirement is simply a different phase of investing. The focus shifts away from aggressive wealth accumulation toward wealth preservation, generating reliable income, reducing unnecessary risk, and ensuring financial confidence throughout retirement.
A successful retirement plan is not about finding the hottest stock or chasing the highest returns. Instead, it involves creating a balanced approach that allows your money to continue working while protecting you from major financial setbacks.
Financial professionals consistently emphasize several key principles that every retiree should understand:
Asset allocation matters more than chasing investment returns.
Diversification helps reduce unnecessary risk.
Protecting your savings is just as important as growing them.
Investment decisions should reflect your age, goals, health, and lifestyle.
A retirement portfolio should evolve over time instead of remaining static.
This guide explains practical strategies that can help retirees grow and protect their money while avoiding some of the most common financial mistakes. Whether you have already retired or retirement is just around the corner, these principles can help you build a stronger financial future.
Why Retirement Planning Doesn’t Stop After Retirement
One of the biggest misconceptions about retirement is that investing becomes unnecessary after leaving the workforce.
Nothing could be further from the truth.
Imagine retiring at age 65. According to current life expectancy trends, many retirees can expect to live into their late 80s or even 90s. That means your retirement savings may need to last for 25 to 30 years or even longer.
If your investments fail to keep pace with inflation, your purchasing power slowly declines.
For example, if inflation averages just 3% annually, something that costs $50,000 today could cost over $90,000 in approximately twenty years.
Without continued investment growth, retirees risk watching their savings lose value in real terms.
This is why retirement investing should focus on maintaining purchasing power rather than simply preserving a fixed dollar amount.
The goal is not maximum growth.
The goal is sustainable growth.
Understanding the Three Goals of Retirement Wealth
Every retirement strategy should revolve around three primary objectives.
Goal One: Protect Your Principal
Most retirees cannot afford major investment losses because they usually have limited opportunities to replace lost income.
During working years, market declines are often temporary setbacks because future earnings continue to fund investments.
Retirees do not enjoy that advantage.
Protecting your retirement savings becomes a priority because recovering from significant losses becomes increasingly difficult as you age.
This doesn’t mean avoiding investments entirely.
It simply means managing risk wisely.
Goal Two: Generate Reliable Income
Your retirement portfolio should produce income that helps pay monthly expenses.
This income may come from several sources:
Social Security
Pensions
Investment dividends
Interest income
Rental properties
Retirement accounts
Passive income becomes increasingly valuable because it reduces reliance on selling investments during unfavorable market conditions.
Goal Three: Continue Growing Your Wealth
Although protection is essential, retirees still need some growth.
Without growth, inflation gradually erodes purchasing power.
Maintaining a portion of your portfolio in investments capable of long-term appreciation helps preserve financial independence throughout retirement.
Balancing growth and safety is one of the cornerstones of effective retirement portfolio management.
The Biggest Financial Risks Facing Retirees
Understanding potential risks helps retirees prepare before problems arise.
Inflation
Inflation is often called the silent wealth killer.
Even modest inflation steadily increases the cost of housing, groceries, transportation, insurance, utilities, and healthcare.
Retirees living on fixed incomes may notice their monthly expenses gradually rising while income remains unchanged.
Including investments with long-term growth potential helps combat inflation.
Market Volatility
Financial markets naturally move through periods of growth and decline.
Many retirees become anxious during market downturns.
Unfortunately, emotional decisions often result in selling investments after prices have already fallen.
Successful retirees understand that volatility is normal.
Instead of reacting emotionally, they rely on a well-designed investment diversification strategy that spreads risk across multiple asset classes.
Longevity Risk
Living longer is wonderful—but it also means needing more money.
Many retirees underestimate how much they will spend during retirement.
Housing maintenance
Healthcare
Travel
Family support
Unexpected emergencies
Long-term care
These costs add up over decades.
Planning for a retirement lasting thirty years rather than fifteen creates a much stronger financial safety net.
Healthcare Costs
Healthcare remains one of retirement’s largest unknown expenses.
Medical costs often increase with age.
Prescription medications
Hospital visits
Specialists
Dental care
Vision care
Long-term care services
Building healthcare expenses into your retirement budget helps avoid unpleasant surprises later.
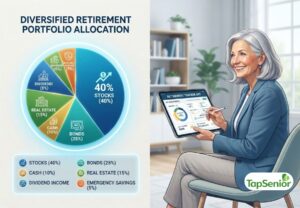
Why Asset Allocation Matters More Than Stock Picking
Many investors spend enormous amounts of time trying to find the perfect investment.
Professional financial advisors often focus somewhere else entirely.
They focus on asset allocation.
Asset allocation refers to how your money is divided among different investment categories.
Examples include:
Stocks
Bonds
Cash
Certificates of Deposit
Real estate
Dividend-paying investments
Alternative investments
Research has consistently shown that asset allocation often has a greater impact on long-term performance than selecting individual securities.
A properly diversified portfolio helps reduce volatility while still allowing opportunities for growth.
For retirees, asset allocation becomes even more important because protecting capital often takes priority over maximizing returns.
The Importance of Diversification
One of the simplest ways to reduce investment risk is diversification.
Rather than placing all your retirement savings into one company, one industry, or one type of investment, diversification spreads risk.
A diversified retirement portfolio may include:
Large-cap stocks
International stocks
Government bonds
Corporate bonds
Cash reserves
Dividend-focused funds
Real estate investments
This approach helps cushion losses if one investment category experiences a downturn.
Diversification does not eliminate risk.
However, it reduces the likelihood that one poor-performing investment will significantly damage your overall retirement savings.
That principle has become even more important during today’s uncertain economic environment, where markets can change rapidly in response to inflation, interest rates, or geopolitical events. Financial experts frequently recommend focusing on diversification and risk-adjusted investing rather than chasing short-term performance.
Should Seniors Invest in Individual Stocks?
Many retirees enjoy investing in individual companies.
There is nothing inherently wrong with owning stocks.
However, individual stock investing requires significant time, knowledge, and discipline.
Successful stock investors regularly analyze:
Quarterly earnings
Management decisions
Industry trends
Competitive advantages
Economic conditions
Valuation metrics
For retirees who prefer a simpler approach, professionally managed investment funds may offer broader diversification and ongoing oversight.
The important question is not whether stocks are “good” or “bad.”
Instead, retirees should honestly ask themselves:
Do I have the time?
Do I understand financial statements?
Can I monitor my investments consistently?
Am I comfortable with significant market swings?
If the answer to several of these questions is “no,” a diversified investment strategy may be more appropriate than relying heavily on individual companies.
Experts often caution older investors against concentrating too much of their retirement savings in only a few individual stocks because doing so increases portfolio risk and requires continuous monitoring.
Finding the Right Balance Between Risk and Reward
Every investment carries some level of risk.
The challenge is choosing a level of risk that matches your financial situation.
A retiree with substantial guaranteed income from pensions and Social Security may be comfortable maintaining slightly higher stock exposure.
Someone relying almost entirely on investment income may choose a more conservative allocation.
There is no universal formula.
Instead, your investment strategy should reflect:
Your age
Your health
Your retirement lifestyle
Expected spending
Family responsibilities
Emergency savings
Legacy goals
Risk tolerance
A personalized financial security plan is always more effective than following generic investment advice.
Avoid Emotional Investing
One of the biggest threats to retirement wealth is emotion.
Fear causes investors to sell after markets fall.
Greed encourages investors to chase investments after prices have already risen dramatically.
Both behaviors can hurt long-term returns.
Successful retirees understand that investing is a marathon rather than a sprint.
They develop a written investment strategy and stick with it during both good markets and difficult ones.
Instead of asking, “What is the market doing today?”
They ask:
“Does my long-term retirement plan still make sense?”
That simple mindset shift often leads to better financial decisions.
Building Confidence Instead of Chasing Perfection
There is no perfect retirement portfolio.
Markets will always experience ups and downs.
Interest rates will change.
Economic conditions will evolve.
Tax laws may be updated.
Healthcare expenses will fluctuate.
Rather than trying to predict every future event, successful retirees focus on building a flexible financial plan capable of adapting over time.
Confidence comes from preparation not prediction.
A thoughtfully designed retirement savings strategy gives retirees the freedom to enjoy life without constantly worrying about every headline or market movement.
Creating a Retirement Income Strategy That Lasts
Accumulating wealth is only one part of retirement planning. Once retirement begins, the focus shifts toward turning those savings into dependable income without exhausting your portfolio too soon.
Many retirees worry about running out of money more than they worry about market declines. This concern is understandable because retirement income often needs to support daily living expenses for twenty to thirty years or longer.
An effective retirement income strategy combines several income sources instead of relying on just one.
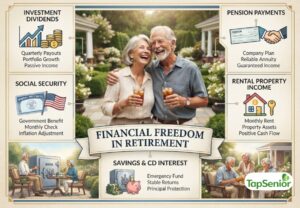
These may include:
Social Security benefits
Employer pensions
Retirement accounts
Investment dividends
Interest from bonds or savings
Rental income
Part-time employment
Other passive income streams
The goal is to create multiple sources of cash flow so that temporary changes in one area do not significantly impact your financial security.
Rather than depending entirely on selling investments during market downturns, retirees who have diversified income sources often enjoy greater stability and peace of mind.
The Bucket Strategy for Retirement
One popular approach to retirement planning is the bucket strategy.
Instead of viewing your retirement savings as one large account, you divide your money into separate buckets based on when you expect to need it.
Bucket One: Immediate Expenses
This bucket contains cash or highly liquid investments that will cover one to three years of living expenses.
Examples include:
Savings accounts
Money market funds
Short-term certificates of deposit
Short-term Treasury securities
Having immediate cash available reduces the likelihood of selling long-term investments during a market decline.
Bucket Two: Medium-Term Income
The second bucket focuses on generating stable income over the next several years.
Possible investments include:
High-quality bonds
Bond funds
Income-producing investments
Conservative balanced funds
These investments generally offer more growth potential than cash while maintaining relatively lower risk.
Bucket Three: Long-Term Growth
The third bucket is designed to keep pace with inflation and provide long-term appreciation.
This bucket may include:
Broad stock market funds
Dividend-focused investments
Large-cap equity funds
International stock funds
Real estate investments
Although these investments fluctuate more in value, they also provide the greatest opportunity for long-term growth.
Using multiple buckets allows retirees to avoid emotional investment decisions while maintaining flexibility.
Why Equity Still Has a Place in Retirement
Some retirees believe they should eliminate stocks entirely after leaving the workforce.
While reducing investment risk makes sense, completely avoiding equities may create another problem.
Without some exposure to stocks, inflation can gradually reduce purchasing power over the years.
Healthcare costs alone often rise faster than general inflation.
Maintaining a reasonable allocation to equities may help retirement savings continue growing.
The exact percentage depends on individual circumstances.
Factors to consider include:
Age
Health
Risk tolerance
Retirement income needs
Other guaranteed income
Legacy goals
Financial advisors often recommend adjusting asset allocation periodically instead of following a fixed rule throughout retirement.
The right balance should reflect your personal situation rather than someone else’s investment strategy.
Financial experts generally recommend reducing excessive equity exposure as retirement approaches while still maintaining a modest allocation for long-term growth and inflation protection.
The Importance of Regular Portfolio Reviews
Retirement planning is not something you complete once and forget.
Your financial situation changes over time.
Investment performance changes.
Tax laws evolve.
Healthcare expenses increase.
Family priorities shift.
A retirement portfolio should be reviewed regularly.
During each review, ask yourself questions such as:
Has my spending changed?
Am I taking too much investment risk?
Do I still have enough emergency savings?
Have my healthcare needs changed?
Is my investment allocation still appropriate?
Do my beneficiaries need updating?
Small adjustments made consistently often prevent larger financial problems later.
Managing Withdrawals Wisely
One of retirement’s biggest challenges is determining how much money can safely be withdrawn each year.
Withdrawing too much increases the risk of depleting savings.
Withdrawing too little may prevent retirees from fully enjoying retirement.
Several factors influence withdrawal decisions:
Portfolio size
Life expectancy
Investment returns
Inflation
Healthcare expenses
Taxes
Unexpected emergencies
Some retirees prefer flexible withdrawals that adjust according to market performance rather than taking the same amount every year.
Regardless of the strategy chosen, the objective remains the same:
Maintain financial stability while allowing investments enough time to continue growing.
Don’t Let Inflation Slowly Steal Your Wealth
Inflation may not seem dramatic from one year to the next.
However, over twenty years, its impact can be enormous.
Items that retirees purchase regularly often experience above-average inflation.
Medical care
Prescription medications
Insurance premiums
Home maintenance
Utilities
Groceries
Transportation
Long-term care
Because of these rising costs, retirees should periodically revisit their retirement budget.
Adjusting spending expectations early helps prevent financial stress later.
Maintaining investments capable of long-term appreciation remains one of the best defenses against inflation.
Healthcare Planning Should Be Part of Every Retirement Plan
Healthcare is one of the largest expenses facing older adults.
Many retirees underestimate these costs.
Beyond routine medical appointments, retirees should consider:
Prescription drugs
Dental care
Vision care
Hearing aids
Rehabilitation
Long-term care services
Home modifications
Caregiver support
Creating a dedicated healthcare savings reserve provides additional financial flexibility during retirement.
Ignoring healthcare planning may force retirees to sell investments unexpectedly when medical expenses arise.
The Value of Emergency Savings
Unexpected expenses never disappear simply because you retire.
Cars need repairs.
Roofs leak.
Appliances fail.
Medical emergencies happen.
Family members occasionally need financial assistance.
An emergency fund helps absorb these unexpected costs without disrupting your long-term investment strategy.
Ideally, emergency savings should remain easily accessible and separate from long-term retirement investments.
Having cash available during emergencies also reduces the temptation to withdraw investments during unfavorable market conditions.
Diversification Is More Important Than Ever
Many retirees mistakenly believe diversification simply means owning several mutual funds.
True investment diversification extends much further.
Diversification includes spreading investments across:
Different asset classes
Different industries
Different geographic regions
Different company sizes
Different investment styles
Different income sources
A diversified retirement portfolio reduces dependence on any single investment.
If one sector experiences a downturn, other investments may help offset those losses.
Diversification does not guarantee profits.
However, it remains one of the most effective tools for managing long-term investment risk.
Common Retirement Investing Mistakes
Even experienced investors occasionally make costly mistakes.
Recognizing these common errors can help retirees protect their wealth.
Becoming Too Conservative Too Soon
Keeping every dollar in cash may feel safe.
However, inflation gradually reduces purchasing power.
A retirement portfolio needs both stability and growth.
Taking Too Much Risk
On the opposite end of the spectrum, chasing high returns through speculative investments may expose retirees to unnecessary losses.
Retirement investing should prioritize consistency over excitement.
Ignoring Asset Allocation
Successful retirement investing depends less on finding perfect investments and more on maintaining an appropriate balance among different asset classes.
Periodic rebalancing helps maintain that balance.
Making Emotional Decisions
Selling after market declines or buying after prices surge often damages long-term performance.
Having a written retirement planning strategy helps reduce emotional investing.
Failing to Plan for Longevity
Many retirees underestimate how long retirement may last.
Planning for thirty years rather than fifteen provides a greater margin of safety.
Should Seniors Continue Investing?
Absolutely.
Retirement does not mean stopping investment altogether.
Instead, it means investing differently.
Younger investors typically focus on aggressive growth.
Retirees generally focus on:
Protecting wealth
Generating income
Managing risk
Keeping pace with inflation
Supporting future healthcare needs
Preserving assets for family members if desired
Investing remains an important part of retirement because financial needs continue throughout life.
The strategy simply becomes more balanced.
Working With a Financial Professional
Some retirees enjoy managing investments independently.
Others prefer professional guidance.
A qualified financial advisor can help:
Build an appropriate retirement portfolio
Determine sustainable withdrawal rates
Reduce investment risk
Improve tax efficiency
Coordinate estate planning
Review insurance needs
Adjust investment strategies during retirement
Even retirees who manage most of their finances independently may benefit from periodic professional reviews.
An objective second opinion can identify opportunities or risks that may otherwise be overlooked.
Preparing for Market Volatility
Market downturns are inevitable.
History shows that financial markets experience corrections, bear markets, and recoveries.
Retirees who prepare emotionally for volatility often make better long-term decisions.
Instead of reacting to headlines, successful investors focus on:
Their investment allocation
Cash reserves
Income needs
Long-term objectives
Diversification
Patience
Market volatility is temporary.
Poor investment decisions made during periods of panic can have lasting consequences.
Maintaining discipline remains one of the most valuable investing skills.
Building a Retirement Legacy
Many retirees eventually shift their attention beyond personal financial security.
They begin thinking about the legacy they want to leave.
This legacy may include:
Supporting children or grandchildren
Helping charitable organizations
Funding educational opportunities
Leaving a family business
Creating generational wealth
Estate planning becomes an important component of wealth preservation.
Regularly updating wills, trusts, beneficiary designations, and powers of attorney helps ensure your wishes are carried out efficiently.
Retirement Is About Freedom, Not Fear
Financial success in retirement is not measured by having the largest investment account.
Instead, it is measured by confidence.
Confidence to travel.
Confidence to spend time with family.
Confidence to enjoy hobbies.
Confidence to handle unexpected expenses.
Confidence to live independently.
A well-designed Retirement Wealth Plan provides that confidence by balancing growth with protection.
Rather than chasing unrealistic investment returns, retirees should focus on building a flexible financial strategy that adapts as life changes.
The most successful retirement plans are rarely the most complicated.
They are built on timeless principles:
Save consistently.
Diversify wisely.
Manage risk carefully.
Review your plan regularly.
Protect against inflation.
Maintain appropriate investment growth.
Prepare for unexpected expenses.
Stay disciplined during market volatility.
Focus on long-term financial security instead of short-term market movements.
Financial experts consistently emphasize that retirees should balance growth with preservation, reduce unnecessary risk, diversify investments, and create a sustainable withdrawal strategy rather than relying on aggressive investment decisions.
Final Thoughts
Retirement represents one of life’s greatest achievements, but it also requires thoughtful financial management. The transition from earning a paycheck to relying on accumulated savings demands a different mindset one focused on protecting wealth while allowing it to continue growing responsibly.
A comprehensive retirement savings strategy is not about predicting the stock market or finding the next winning investment. Instead, it is about making informed decisions that support your lifestyle today while safeguarding your financial future for the decades ahead.
Whether you are just beginning your retirement journey or have already been retired for several years, it is never too late to strengthen your financial foundation. By embracing long-term investing, maintaining smart asset allocation, practicing investment diversification, and prioritizing financial security, you can build a retirement that offers not only financial stability but also the freedom to enjoy the years you’ve worked so hard to achieve.
Bài viết liên quan: